
D&A Planning After the One Big Beautiful Bill Act
After 2021, whether an expenditure was deducted currently or recovered through depreciation often affected timing, but it typically did not create a meaningful advantage from a Section 163(j) perspective. The restoration of depreciation, amortization, and depletion addbacks in the computation of adjusted taxable income (“ATI”) has changed that analysis and created a new opportunity for taxpayers with actual or anticipated interest limitation exposure. As a result, taxpayers should reconsider whether certain expenditures that historically may have been deducted immediately can instead be capitalized into depreciable or amortizable property in order to improve their Section 163(j) profile.
READ MORETAX COURT ROUND-UP – January 2023
I'm new here, but I know enough not to try to do what everyone else does. I won't try to cover the wider tax picture. I cover United States Tax Court on my blog, so here's a brief round-up on what went on in Tax Court during the last month that I think is of interest to the tax planner and practitioner...
Read More
Live Webinar Event: The DeFi & Digital Asset Taxation Course
Join nationally recognized speaker and educator Matt Metras, EA, as he guides you through the ins and outs of mining, staking, forks, airdrops, DeFi swaps, yield farming, liquidity pools, NFTs, and more. With little guidance in these areas, you'll learn how to apply existing code sections to cryptocurrency situations, with a focus on finding tax-saving opportunities. We'll also cover how to extract transactions from the blockchain and introduce you to a number of helpful tools. This two-hour course is packed with valuable information, but it’s more than just information - we're also offering continuing education credits to qualifying attendees, courtesy of the American Institute of Certified Tax Planners.
Read More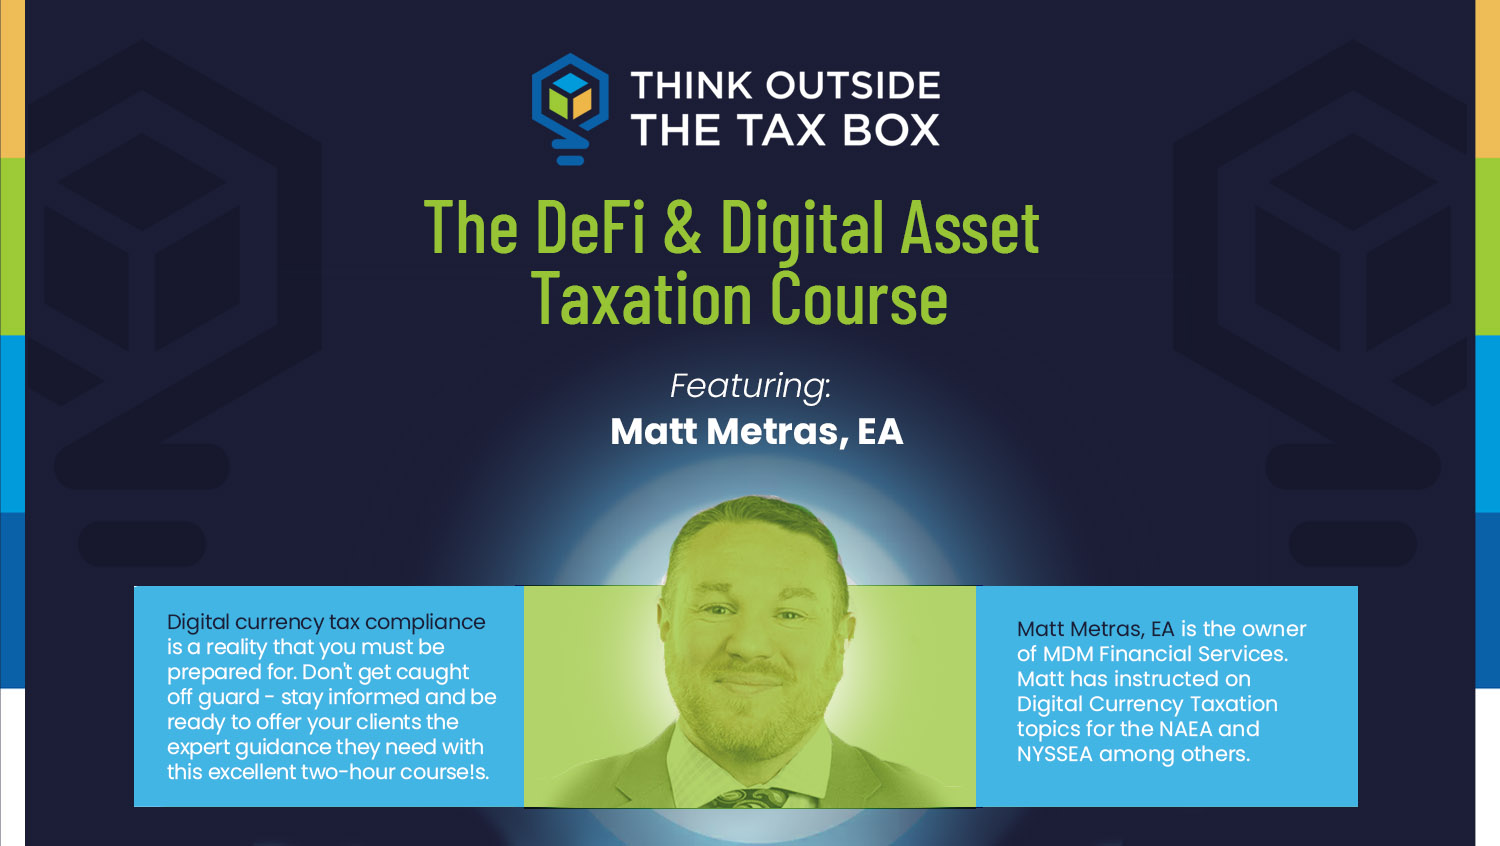
Year End Tax Saving Tips for the Digital Currency Investor
As a financial expert, I know that 2022 has been a roller coaster year for investors. With only days left in the year, the Dow is down and the S&P 500 is down . On the high-risk crypto side, Bitcoin has fallen 64 percent and former Top 10 coin Solana has fallen more than 92 percent thanks to Sam Bankman-Fried and FTX. While the markets may be down, taxpayers can still come out ahead through careful tax planning. By taking the time to assess your financial situation and make strategic decisions, you can minimize their tax burden and potentially save money. It's important to consult with a tax planning professional to ensure that you’re taking advantage of all available tax savings opportunities. Here are a few of the things to do before the clock strikes midnight on New Year’s Eve.
Read More
Inflation Reduction Act – Energy Credits for Your Home
The Inflation Reduction Act has brought back and revised credits we have seen before. One of these credits had a $500 lifetime value but now can be $1,200 for each eligible tax year. That is a potential $11,500 increase in savings for your clients. They do not have to build a new house to take advantage of these savings. Taxpayers can receive this credit for improvements made to their home. The tax savings do not stop there. If your client buys an electric vehicle, they are going to need somewhere to charge it, right? Well, the Inflation Reduction Act has considered that, too. Homeowners can save an extra $1,000 on their taxes by installing the charging equipment at home. Let's explore how you can help your non-business clients capitalize on these types of tax savings on these improved energy credits. We will look at both credits now.
Read More
Making Smarter Retirement Account Distributions by Asking When, Why, and Where
As a proactive client, you often ask your tax professional about the tax effects of taking distributions from your retirement accounts. Unfortunately, it seems that proactive clients are in the minority. More often, your tax professional only learns about your retirement account distribution when the Form 1099-R arrives with your other tax documents. Proactive tax planners can improve their tax savings strategies by asking the when, where, and why that can help reduce negative tax consequences and can make you look like a problem-solving rock star to your clients. Whether you are looking for proactive ideas to implement on your own, or you want to be a problem-solving rock star with your tax planning clients, keep reading to learn how to make smart retirement account distributions.
Read More
Don’t Forget the Cohan Rule but Try Not to Need It
We are creeping up to the centennial of the Cohan rule. Learned Hand’s opinion for the Second Circuit in Cohan v. Commissioner came out on March 3, 1930 . I love this rule so much that I've made it the Prime Directive in my own book, Reilly’s Laws of Tax Planning: “If you don’t have documentation, at least have a plausible story.” However, subsequent legislation, changes in societal expectations, and the passage of time have eroded the usefulness of the Cohan rule for taxpayers. In recent years, there have been more instances of courts refusing to apply it than allowing its use. That’s why in Reilly’s Sixteenth Law of Tax Planning, I advise people to “being right without substantiation can be as bad as being wrong.”
Read More
Using S Corporations to Minimize FICA And Medicare Tax
When United States Tax Court Judge Paris issued the opinion in the case of Ryan Fleischer in 2016 , it caused quite a stir in the tax blogosphere. And from what I have been able to gather off the record it remains of interest. The Fleischer decision makes it very difficult, if not impossible for some financial professionals to use S corporations to mitigate self-employment tax. Rather than attack on reasonable salary, the IRS took an assignment of income approach, which succeeded throwing planners for financial professionals like Fleischer into a bit of an uproar...
Read More
Inflation Reduction Act — The Residential Clean Energy Credit
Your clients may think that business owners get all the tax breaks and incentives. But that’s not quite true. We see that with the expansion of clean energy tax credits in the Inflation Reduction Act. One of the goals of the Inflation Reduction Act is to address climate change. The bill does this by helping taxpayers save green for using green energy. Taxpayers can not only enjoy tax benefits from riding clean the next 10 years. Your environmentally conscious clients can also reduce their tax bill as they make clean energy changes to their home. What client do you have right now that would enjoy claiming 30% of the costs of their home improvements for a tax credit? Not sure? Well get your pen and paper to make a list while we go over how this new credit can save them this tax year until 2034.
Read More

D&A Planning After the One Big Beautiful Bill Act
After 2021, whether an expenditure was deducted currently or recovered through depreciation often affected timing, but it typically did not create a meaningful advantage from a Section 163(j) perspective. The restoration of depreciation, amortization, and depletion addbacks in the computation of adjusted taxable income (“ATI”) has changed that analysis and created a new opportunity for taxpayers with actual or anticipated interest limitation exposure. As a result, taxpayers should reconsider whether certain expenditures that historically may have been deducted immediately can instead be capitalized into depreciable or amortizable property in order to improve their Section 163(j) profile.
What To Watch Out For With Family Limited Partnerships
The story of Anne Milner Fields is one of the reasons family limited partnership (FLP) opinions appeal to me so much. Born in 1925, she grew up in a small town in Texas and then moved to Dallas where she got a job as a secretary and met prominent oil man Bert Fields Sr. They married, and she lived the life of a socialite until he died in 1963. She consciously turned herself into a businesswoman, going so far as to take accounting courses. Having no children or grandchildren, she took her grandnephew, Bryan Milner, under her wing, paying for his education and mentoring him. In 2010, the year she turned 85, she made him executor of her estate and gave him a general power of attorney. He was also set to inherit the residue of her estate after some specific bequests. I really think we have the elements of a novel or a TV miniseries here, but we are tax people, so we are going to focus on how Anne’s estate tax was handled after she passed. It didn’t go well.

Tax Research in an AI World
It has never been harder to do quality tax research than at any time in my 43-year career in tax accounting. In the 1980s, when I was part-time in the industry, there was no internet. Since I was part-time, I ordered Publications 1132, 17, and 334. The rest I found at the library. A few hearty souls might even remember when the post office had stacks of tax forms for the public. Once I went full-time for the 1989 tax season I needed more resources. CCH was my tool of choice. I still used IRS publications and the library. My handy reference guide of choice was, and still is, the QuickFinder. I never used TaxBook much, but it is another good resource for general answers. Then came the internet. The promise was that we would have the world at our fingertips. And for the large part we did, only we forgot some things we would rather keep at an arm’s length. The internet slowly allowed us to replace rooms in our office filled with tax guides and forms with online resources. Law offices and accounting firms often wrote tax articles on narrow tax subjects. Research was easier than ever.
Then came AI.
