
Trump Accounts Are Live. Are They Spectacular?
Trump Accounts (or § 530A accounts) went live via app on July 4, 2026. According to the Treasury Department, over six million accounts have been opened. As of Monday, July 6, 2026, parents and guardians of account beneficiaries could use the app to view their children’s accounts, fund the accounts, and access balances and financial education information. The Treasury Department designated BNY Mellon “as a financial agent of the U.S. government to support implementation of the new Trump Accounts program.” BNY, in partnership with Treasury, will manage the accounts and help to develop the app taxpayers can use to manage their accounts. Robinhood Securities, LLC is acting as the initial trustee and brokerage for the accounts.
READ MOREBuilding a Partnership the Right Way: Tax Strategies From Day One
Setting up a partnership is a lot like getting married. It's exciting, full of promise, and if you do it right, it can be incredibly rewarding. Do it wrong, and you're setting yourself up for years of headaches and potentially significant financial loss. The decisions you make at the formation stage of your partnership will impact your tax situation for years to come, and in some cases, these decisions can be difficult or costly to undo later. In this article, we'll explore the critical steps in setting up a partnership and the tax implications of various contribution strategies. You'll learn how to establish a foundation that maximizes tax advantages from day one.
Read More
The AI-Enhanced CPA: How to Automate Repetitive Work and Reclaim Advisory Time
There has never been a moment in the accounting profession, quite like this one. For decades, new tools have promised efficiency and accuracy, but artificial intelligence is different. AI is not just another tool, it’s a change in how we work. AI can automate tasks that were formerly part of our everyday work, such as data entry, reconciliations, reporting, and even initial research.
Read More
Worrisome Messages Subtly Delivered Via Recent Tax Developments
Tax professionals are inundated with tax developments from all branches of the government and from all levels of government on a daily basis. Our technical tax knowledge expands weekly. Given the immensity of tax law changes in P.L. 119-21 (July 4, 2025), informally named the One Big Beautiful Bill Act (OBBBA), and the guidance we’ll continue to get over the next few years along with non-OBBBA updates, we might run out of time and bandwidth to step back and ask what additional relevance this guidance, as well as various reports issued by the government every day, mean for the well-being of our tax system. This article unpacks select tax law changes and government documents to offer four subtle messages within them. Generally, the messages don’t bode well for an effective tax and revenue system. The article ends with some suggestions on what can help improve our tax system.
Read More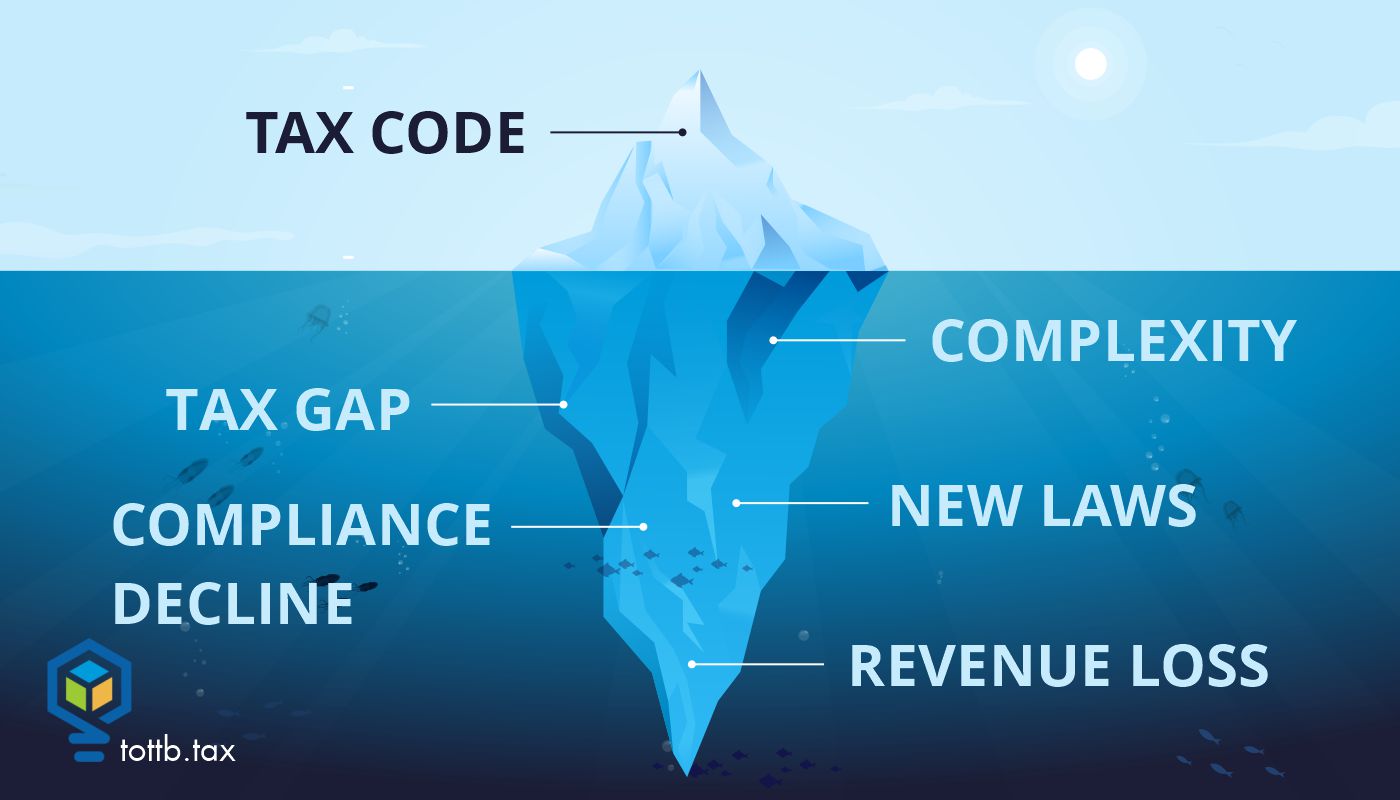
Sirius Solutions and the S Corp or Partnership Choice
The Fifth Circuit Court of Appeals opinion in Sirius Solutions L.L.L.P. v. Commissioner may change our views of entity choice. If the decision holds up, partnerships will be able to effectively make the portion of limited partner income subject to self-employment tax whatever they want, including zero. This contrasts with the IRS position upheld by the Tax Court in Soroban Capital that treated all of the income of limited partners who were active in the business as self-employment income.
Read More
Niche Down to Scale Up: How Specialization Drives Visibility and Profitability
For many accountants, narrowing our focus can feel risky. We are trained to serve anyone who needs help and provide stability in any financial situation. Choosing a niche often raises concerns: Will we turn away good clients? Will we limit opportunities or reduce business stability? These are common doubts many of us have faced in our careers.
Read More
TAX COURT ROUNDUP – May 2026
April brings both anomalies and the same-old from Tax Court. Congressional enactments that misfire give opportunities to inventive practitioners, while self-represented petitioners continue to do the darndest things. All these are teaching moments that make "the small court" a continuing professional education course that never ends.
Read More
2026 Summer Education Series Event Calendar
Think Outside the Tax Box is thrilled to bring you the 2026 Summer Education Series, sponsored by Sandy Bay! The fifth installment of this beloved annual series, we will be bringing our loyal subscribers monthly webinars featuring some of the brightest minds in tax all summer long. Each webinar will feature our usual blend of high-quality education and entertainment and include continuing education credits for those who qualify. All of this is included in your regular subscription! Continue reading to see what we have in store...
Read More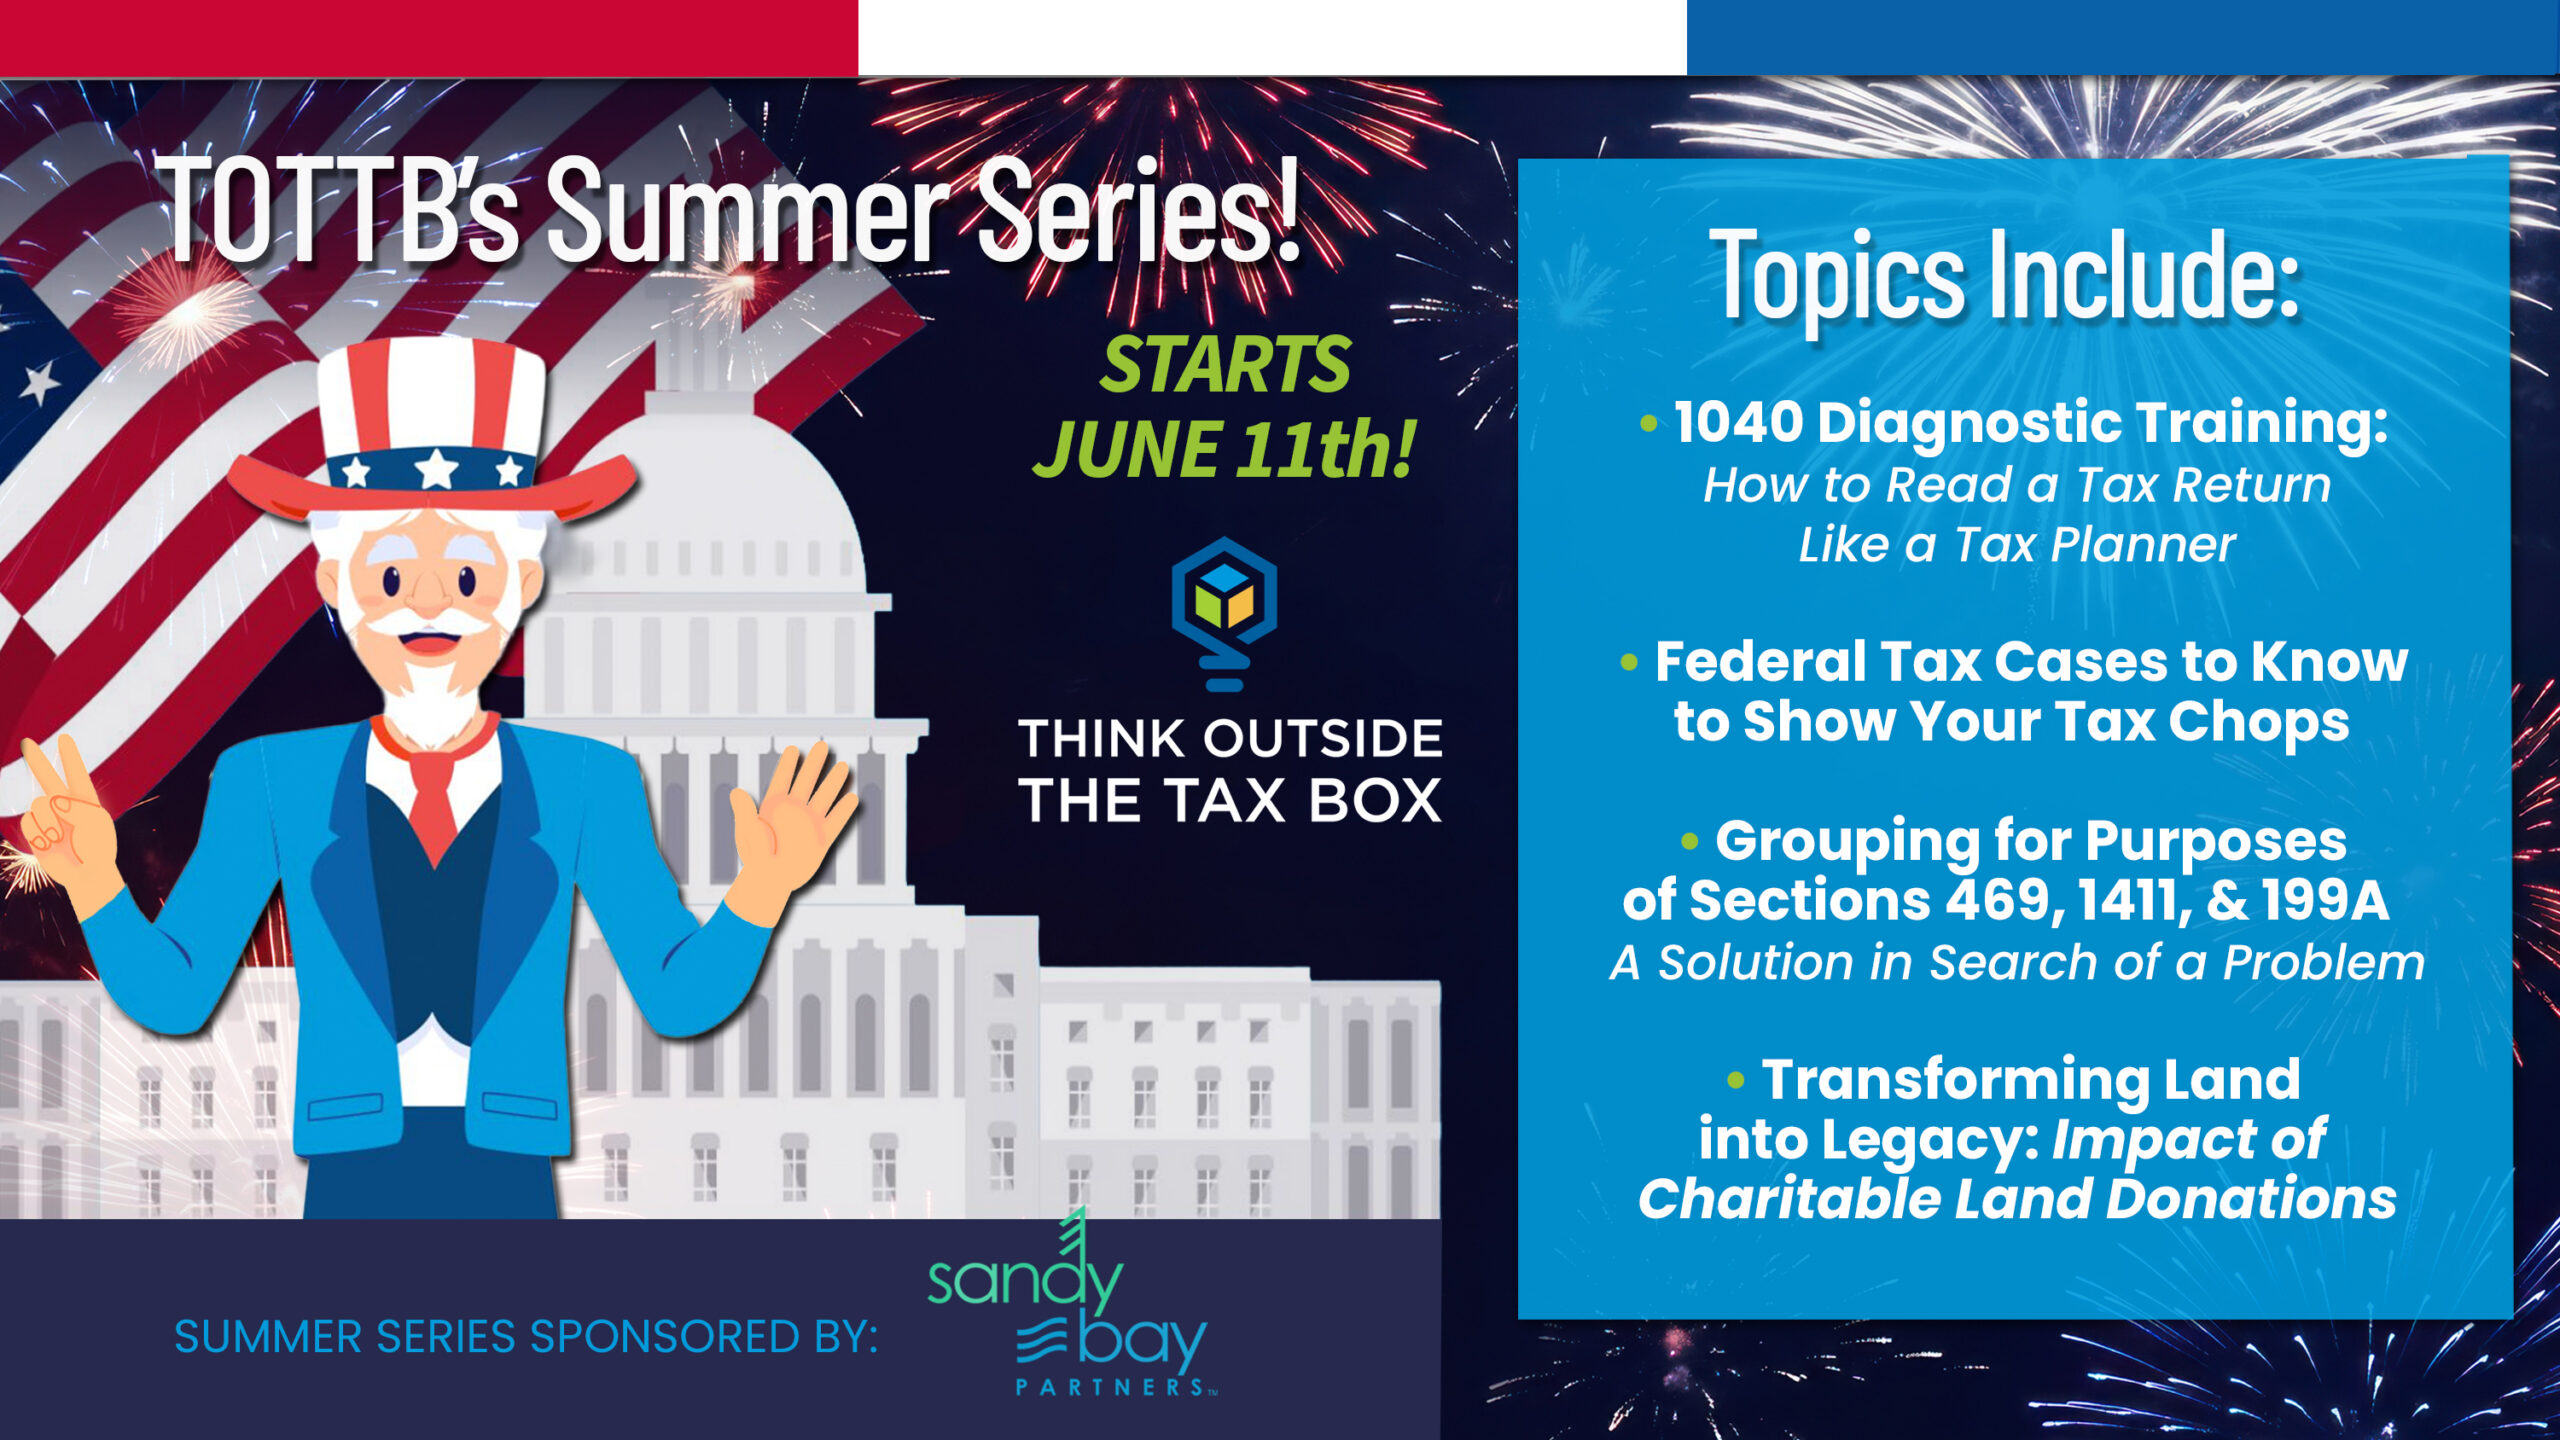
Tax Loss Harvesting with Cryptocurrency
In the Fall of 2025, Bitcoin reached an all-time high of over $120,000. Since then, it fell over 40% to under $70,000 in the first quarter of 2026, before slightly recovering, currently resting around $75,000 as of this writing. With the steep drop in the price of Bitcoin and other cryptocurrencies, a common question from taxpayers is whether they can use the current losses to offset their other income. Large investors and professionals such as Grant Cardone and Shehan Chandrasekera (Head of Tax Strategy at Cointracker) have suggested that cryptocurrency can be sold and bought back immediately to claim the tax benefits. As with most things, the answer to this is not as simple as they portray, and many commentators, influencers, and sometimes professionals, miss the intricacies of cryptocurrency taxation.
Read More

Trump Accounts Are Live. Are They Spectacular?
Trump Accounts (or § 530A accounts) went live via app on July 4, 2026. According to the Treasury Department, over six million accounts have been opened. As of Monday, July 6, 2026, parents and guardians of account beneficiaries could use the app to view their children’s accounts, fund the accounts, and access balances and financial education information. The Treasury Department designated BNY Mellon “as a financial agent of the U.S. government to support implementation of the new Trump Accounts program.” BNY, in partnership with Treasury, will manage the accounts and help to develop the app taxpayers can use to manage their accounts. Robinhood Securities, LLC is acting as the initial trustee and brokerage for the accounts.
Will AMT Make a Comeback After OBBBA?
Following Betteridge’s Law of Headlines, the answer to the question posed in the headline is, “no.” Actually — because we’re talking about taxes here — we can say the answer is never so definitive, so let’s change it to “probably not.” But it’s more complicated than it may seem.
Why Citizenship, Residency, and Domicile Matter
If you spend any time in the world of cross-border taxes, you start to notice a pattern: the hardest problems usually begin with a deceptively simple question—who gets to tax you? And the answer is rarely as simple as “the country where I live.” That’s because tax systems don’t rely on just one concept to decide who belongs in their net. They use citizenship, residency, and domicile. These terms sound similar, and people often use them interchangeably in casual conversation, but in tax law they mean very different things. For globally mobile individuals, understanding the difference matters. You can be a U.S. citizen, a tax resident of another country, and still have your long-term home base tied to a different jurisdiction altogether. Each label can trigger different tax consequences, different filing obligations, and different planning opportunities.
