
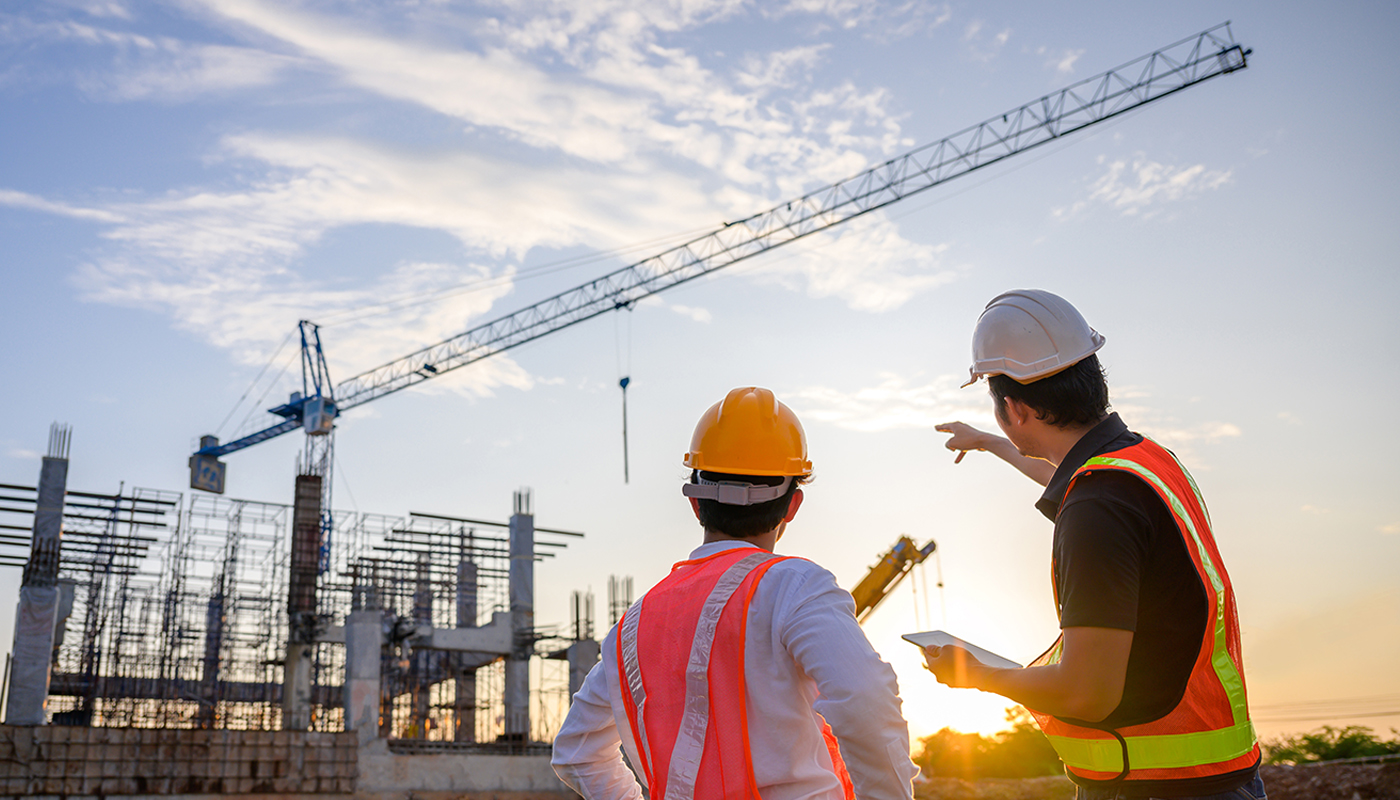
D&A Planning After the One Big Beautiful Bill Act
After 2021, whether an expenditure was deducted currently or recovered through depreciation often affected timing, but it typically did not create a meaningful advantage from a Section 163(j) perspective. The restoration of depreciation, amortization, and depletion addbacks in the computation of adjusted taxable income (“ATI”) has changed that analysis and created a new opportunity for taxpayers with actual or anticipated interest limitation exposure. As a result, taxpayers should reconsider whether certain expenditures that historically may have been deducted immediately can instead be capitalized into depreciable or amortizable property in order to improve their Section 163(j) profile.
READ MORE10 Ways CTPs Can Use the New Adobe AI Assistant to Analyze PDFs
Launched as a beta in February 2024, the Adobe AI Assistant is a generative AI-powered conversational engine feature within Adobe Acrobat. The app enables you to “chat” with PDF files in natural language and unlock new levels of document productivity. The AI Assistant can be likened to a knowledgeable librarian for digital documents. Just as a librarian assists you in finding the right books, navigating through complex archives, and answering detailed inquiries about content, the AI Assistant helps users navigate, understand, and extract key information from PDF documents. It provides summaries, clarifies content through answers and suggestions, and links to relevant sections, all designed to make your interaction with digital documents as enriching and efficient as a visit to a well-staffed library.
Read More
What Clients Should Know About Innocent Spouse Relief
Some clients marry into tax trouble – and then have no clue how to get out. Others are on the cusp of a separation or divorce and want the uncoupling (at least in the eyes of tax authorities) to start ASAP. Few clients who need the IRS tool called “innocent spouse relief” to unshackle themselves from a spouse’s tax mess (either one that spouse brought to the marriage or one they racked up later) seem to know about it. Here’s what to tell such a client about what this relief does and does not cover and what your client will have to prove before they can qualify – as well as how difficult this relief can be to get.
Read More
TAX COURT ROUNDUP – June 2024
No dramatic developments this month, but some technical inputs worth noting. A good practitioner is always learning; it's so much better to learn from other peoples' mistakes than one's own.
Read More
Life Cycle of a Cost Segregation Study
The concept of cost segregation began in the 1960s, when taxpayers argued specific components of real estate had a shorter life than the depreciation tables allowed (39 years for commercial property and 27.5 years for residential real estate). After decades of legal cases, the IRS provided rules and safe harbors in 1996 and 2002. Taxpayers now can use cost segregation and remain compliant with IRS regulations. The real question now is: Does a cost segregation study really reduce a taxpayer’s liability? And if so, by how much?
Read More
Three Rules for the Augusta Rule
Today I want to talk about the quick question, “Can I rent my home to my business tax free?” The answer is not straightforward. It takes time to look at the specific set-up of that taxpayer's business. It requires a bit of research. You need to know things like: ● What's the fair market value of renting your home? ● How many days will you rent your home to your business? ● Can we substantiate that this rental is ordinary and necessary? Amber Gray-Fenner already did an excellent job of explaining the Augusta Rule in an earlier issue of the newsletter. So, I won't go over all the same points. I want to look at what the Augusta Rule is and how it came about. Then, we'll look at three takeaways for you to remember in your practice and give to your clients.
Read More
Death and Taxes: What Clients Should Know About the Death of a Spouse
Even your most financially savvy client isn’t going to think clearly after the death of their spouse. Taxes will be last on their minds. That’s where you’ll come in, nudging them toward tax and money moves both immediate and long-term, from filing returns to budgeting income to taking a step-up in basis. Above all, don’t assume grieving clients know these details or that they’ll remember them in one of life’s toughest moments.
Read More
Looking Bad for Investors in Syndicated Conservation Easements
Albert Lauber, my favorite Tax Court judge, gave us an opinion in February that paints a detailed picture of the workings of a syndicated conservation easement. In the end, he supports the findings of the Senate Joint Finance Committee that the engine of these abusive transactions is an inflated appraisal. In November, David Gustafson issued an opinion that exposed the financial engineering techniques that promoters engaged in. We’ll take a look at those, but first I would like to give you an overview, because we may need that to figure out the lessons to be learned.
Read More
Avoid IRS Red Flags in Multiple Business Strategies: A Guide for the Wary Tax Business Owner
In the labyrinth of tax planning and business structure, the path to protecting your client’s multiple business strategy from the ever-watchful eye of the IRS can be as intricate as a well-played game of chess. However, while the strategic moves might be complex, the rules of the game are quite clear. Today, let’s dissect these rules with a blend of cautionary tales and cheeky wisdom, ensuring your business maneuvers stay sharp and IRS-compliant. Ever heard of the tax strategy to just “create a new C corporation” and shift income by paying management fees from your main company? Well, so has the IRS, and they are highly skeptical when they see it in the field. The Aspro, Inc. v. Commissioner case serves as a stark reminder for taxpayers about the importance of meticulous documentation and the strict adherence to IRS guidelines for deducting management fees. Aspro, an Iowa-based C corporation in the asphalt-paving business, faced scrutiny over its practice of paying "management fees" to its shareholders, which the IRS and subsequent court rulings reclassified as non-deductible disguised dividends.
Read More

D&A Planning After the One Big Beautiful Bill Act
After 2021, whether an expenditure was deducted currently or recovered through depreciation often affected timing, but it typically did not create a meaningful advantage from a Section 163(j) perspective. The restoration of depreciation, amortization, and depletion addbacks in the computation of adjusted taxable income (“ATI”) has changed that analysis and created a new opportunity for taxpayers with actual or anticipated interest limitation exposure. As a result, taxpayers should reconsider whether certain expenditures that historically may have been deducted immediately can instead be capitalized into depreciable or amortizable property in order to improve their Section 163(j) profile.
What To Watch Out For With Family Limited Partnerships
The story of Anne Milner Fields is one of the reasons family limited partnership (FLP) opinions appeal to me so much. Born in 1925, she grew up in a small town in Texas and then moved to Dallas where she got a job as a secretary and met prominent oil man Bert Fields Sr. They married, and she lived the life of a socialite until he died in 1963. She consciously turned herself into a businesswoman, going so far as to take accounting courses. Having no children or grandchildren, she took her grandnephew, Bryan Milner, under her wing, paying for his education and mentoring him. In 2010, the year she turned 85, she made him executor of her estate and gave him a general power of attorney. He was also set to inherit the residue of her estate after some specific bequests. I really think we have the elements of a novel or a TV miniseries here, but we are tax people, so we are going to focus on how Anne’s estate tax was handled after she passed. It didn’t go well.

Tax Research in an AI World
It has never been harder to do quality tax research than at any time in my 43-year career in tax accounting. In the 1980s, when I was part-time in the industry, there was no internet. Since I was part-time, I ordered Publications 1132, 17, and 334. The rest I found at the library. A few hearty souls might even remember when the post office had stacks of tax forms for the public. Once I went full-time for the 1989 tax season I needed more resources. CCH was my tool of choice. I still used IRS publications and the library. My handy reference guide of choice was, and still is, the QuickFinder. I never used TaxBook much, but it is another good resource for general answers. Then came the internet. The promise was that we would have the world at our fingertips. And for the large part we did, only we forgot some things we would rather keep at an arm’s length. The internet slowly allowed us to replace rooms in our office filled with tax guides and forms with online resources. Law offices and accounting firms often wrote tax articles on narrow tax subjects. Research was easier than ever.
Then came AI.
