
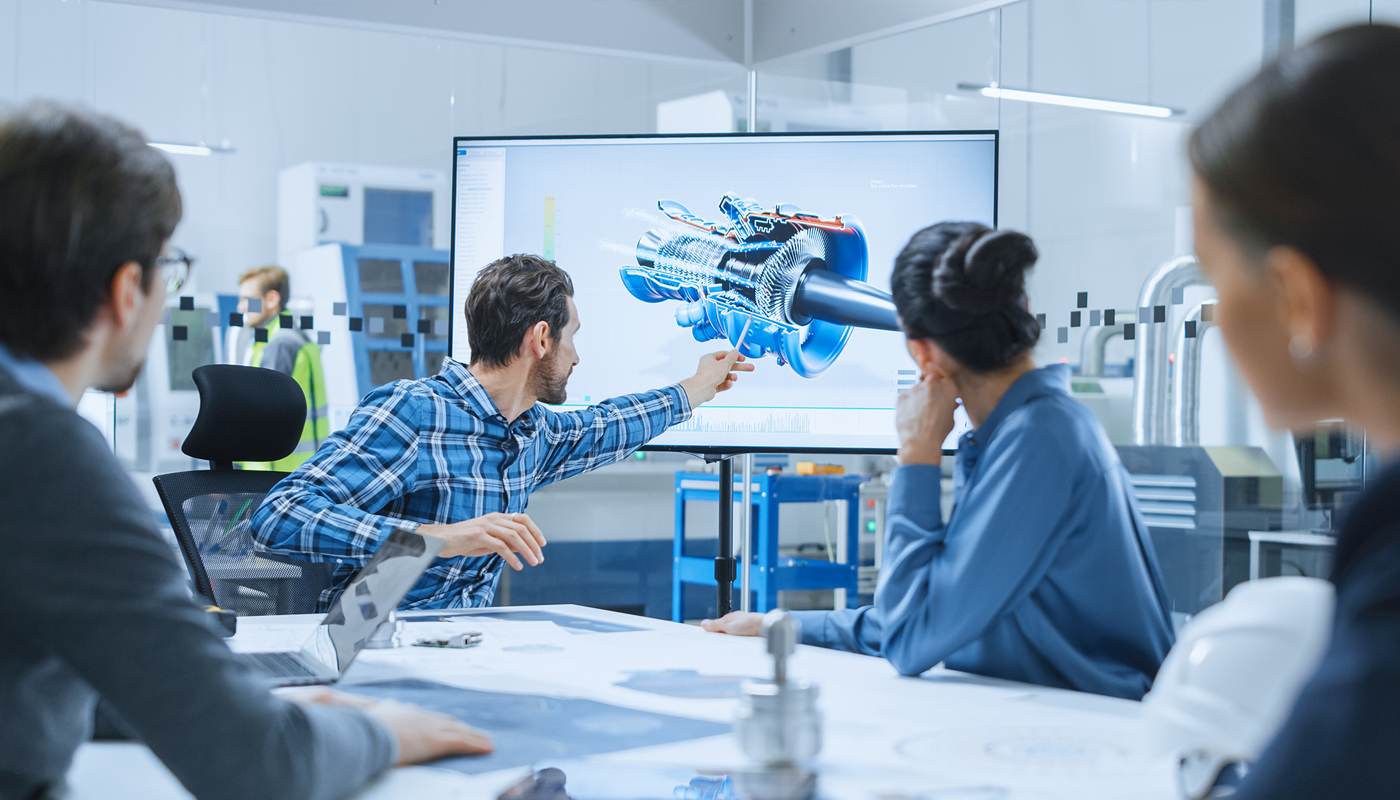
Reassessing R&D Structures After the Section 174 Changes
Recent changes to the tax treatment of research and experimental (“R&E”) expenditures may warrant a fresh look at existing intellectual property (“IP”) and research and development (“R&D”) structures. This article examines whether taxpayers should revisit decisions regarding the location of R&D activities, IP ownership, contract R&D arrangements, and related transfer pricing policies in light of the evolving legislative landscape, and how the interaction of Sections 174, 168(k), 59(e), and 163(j) can be used to calibrate a tax-efficient result.
READ MOREIns and Outs of IRS CCA 202302011 on Cryptocurrency Losses
Here are a few reminders on claiming losses from property transactions with a focus on an informal ruling the IRS issued in January 2023 to help explain losses from certain cryptocurrency transactions. This article focuses not only on what CCA 202302011 provides, but also what it doesn’t cover regarding possible losses from cryptocurrency and digital asset transactions. Click here to continue reading…
Read More
Sophisticated Charity Plan Where Everything Goes Wrong
The story of Scott M. Hoensheid’s charitable planning gone awry as related by Judge Joseph W. Nega of the United States Tax Court is an interesting one. Click here to continue reading…
Read More
Are NFTs “Collectibles”? – The IRS Says Maybe
Beanie babies, Pokémon cards, POGs, and digital pictures of monkeys on the internet, one of these things is not like the others. All these are items that people may collect or at least have collected in the past. Maybe they were just collecting for fun, or perhaps they acquired in hopes of selling their items in the future for a profit. However, the IRS has highlighted only one of the items on this list as potentially being a collectible. A non-fungible token (NFT) “is a unique digital identifier that is recorded using distributed ledger technology and may be used to certify authenticity and ownership of an associated right or asset. Ownership of an NFT may provide the holder a right with respect to a digital file (such as a digital image).” NFTs run the gamut from bored apes (computer generated pictures of monkeys that sell for hundreds of thousands of dollars, not to be confused with board apes, which are monkey pictures on sandwich and surf boards and do not sell for hundreds of thousands of dollars) to Ruish Bronzelight (a DeFi Kingdoms online video game Warrior Wizard we met in “Tax Planning for DeFi Based Games”), and even event tickets (especially popular with crypto conferences). There is even at least one CPA who sells access to his tax practice via NFT. Click here to continue reading…
Read More
Tax Court Roundup June 2023
This month I've decided to change format. I'm grouping Tax Court thumbnails by category. Not every reader deals with every issue. But coverage is still useful even where only a few specialize. Click here to read the latest happenings!
Read More
An Overview of the Risks and Possibilities of Related Party Exchanges
IRC § 1031 exchanges have the ability to confer substantial financial benefits to taxpayers. Although taxpayers may use § 1031 to place themselves in a superior economic position, taxpayers may not exploit this section in an abusive manner. Taxpayers can use exchanges to give themselves different types of benefits, but one of the primary benefits is the deferral of federal income tax. When conducted correctly, 1031 exchanges are regarded as a form of legitimate tax avoidance. One of the main issues involved with these transactions is determining the boundaries between abusive tax avoidance and non-abusive tax avoidance. In the context of “related party exchanges” – i.e. those transactions which involve subsection 1031(f) – this issue shows up in a relatively complex fashion, because the related party rules are not well understood by most practitioners. Furthermore, determining abusive tax avoidance with related party exchanges is difficult because of the scarcity of case law. Based on the case law which we have, and on the other authoritative references, we can put together a reasonable overview of the risks of related party exchanges. This overview should prove useful when providing expert counsel to taxpayers seeking to conduct this type of transaction. For direct exchanges, the 2-year ownership rule found in 1031(f)(1)(C) should be used as the dominant source of guidance. For “indirect exchanges,” taxpayers must be aware of the higher levels of risk involved, as there is a greater possibility of abusive tax avoidance. To read more click here!
Read More
Famous Bad Citizens and the Code That Caught Them – Al Capone
At its peak, Alphonse (Al) Capone’s criminal empire was worth approximately $1.3 billion when adjusted for inflation. On June 5, 1931, Capone was indicted on multiple counts of income tax evasion. At the time the maximum penalty for his offenses was 32 years in jail and $80,000 in fines (almost $1.6M in inflation adjusted dollars). The prosecution in Capone’s case “documented Capone's lavish spending, evidence of a colossal income. The government also submitted proof that Capone was aware of his obligation to pay federal income tax but failed to do so." Click here to keep reading about this fascinating case…
Read More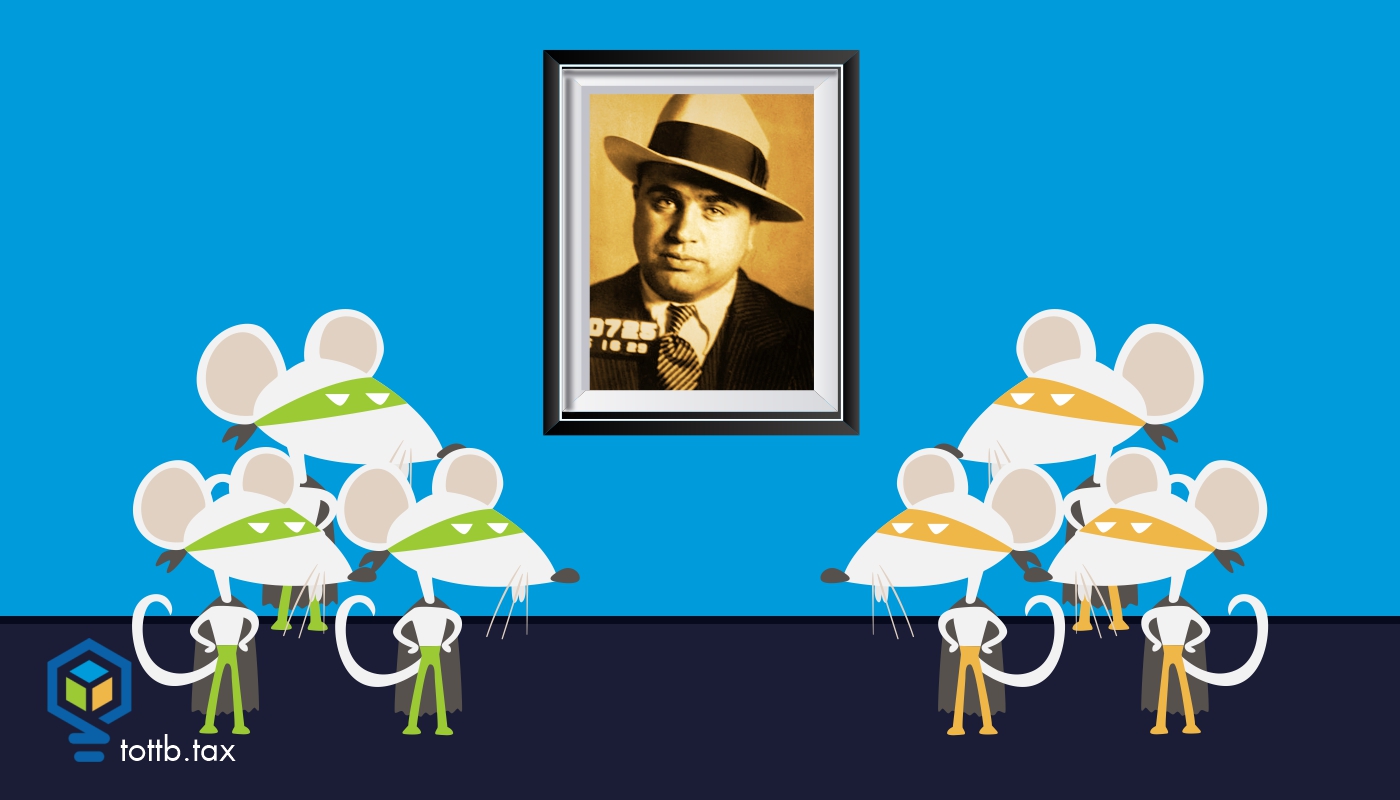
Vehicle and Mileage Issues – Real-World Best Practices and Maximizing Deductions in a Tax Plan
Every tax professional has at least one client that when asked about business mileage replies, “I don’t know; what did I have last year?” You may have read that last sentence and thought, “most of them.” Self-employed taxpayers generally know they must track their mileage, but it’s seldom done correctly, or at all. Vehicle deductions are an area frequently challenged by the IRS on examination as well as an area the taxpayer is unlikely to prevail without strong, contemporaneous documentation. That said, very few taxpayers keep perfect records, so what are the best practices for mileage deductions in the real world? Keep reading to find out!
Read More
Trump Indictment: An Accountant’s Perspective
IRC § 1031 exchanges have the ability to confer substantial financial benefits to taxpayers. Although taxpayers may use § 1031 to place themselves in a superior economic position, taxpayers may not exploit this section in an abusive manner. Taxpayers can use exchanges to give themselves different types of benefits, but one of the primary benefits is the deferral of federal income tax. When conducted correctly, 1031 exchanges are regarded as a form of legitimate tax avoidance. One of the main issues involved with these transactions is determining the boundaries between abusive tax avoidance and non-abusive tax avoidance. In the context of “related party exchanges” – i.e. those transactions which involve subsection 1031(f) – this issue shows up in a relatively complex fashion, because the related party rules are not well understood by most practitioners. Furthermore, determining abusive tax avoidance with related party exchanges is difficult because of the scarcity of case law. Based on the case law which we have, and on the other authoritative references, we can put together a reasonable overview of the risks of related party exchanges. This overview should prove useful when providing expert counsel to taxpayers seeking to conduct this type of transaction. For direct exchanges, the 2-year ownership rule found in 1031(f)(1)(C) should be used as the dominant source of guidance. For “indirect exchanges,” taxpayers must be aware of the higher levels of risk involved, as there is a greater possibility of abusive tax avoidance. To read more click here!
Read More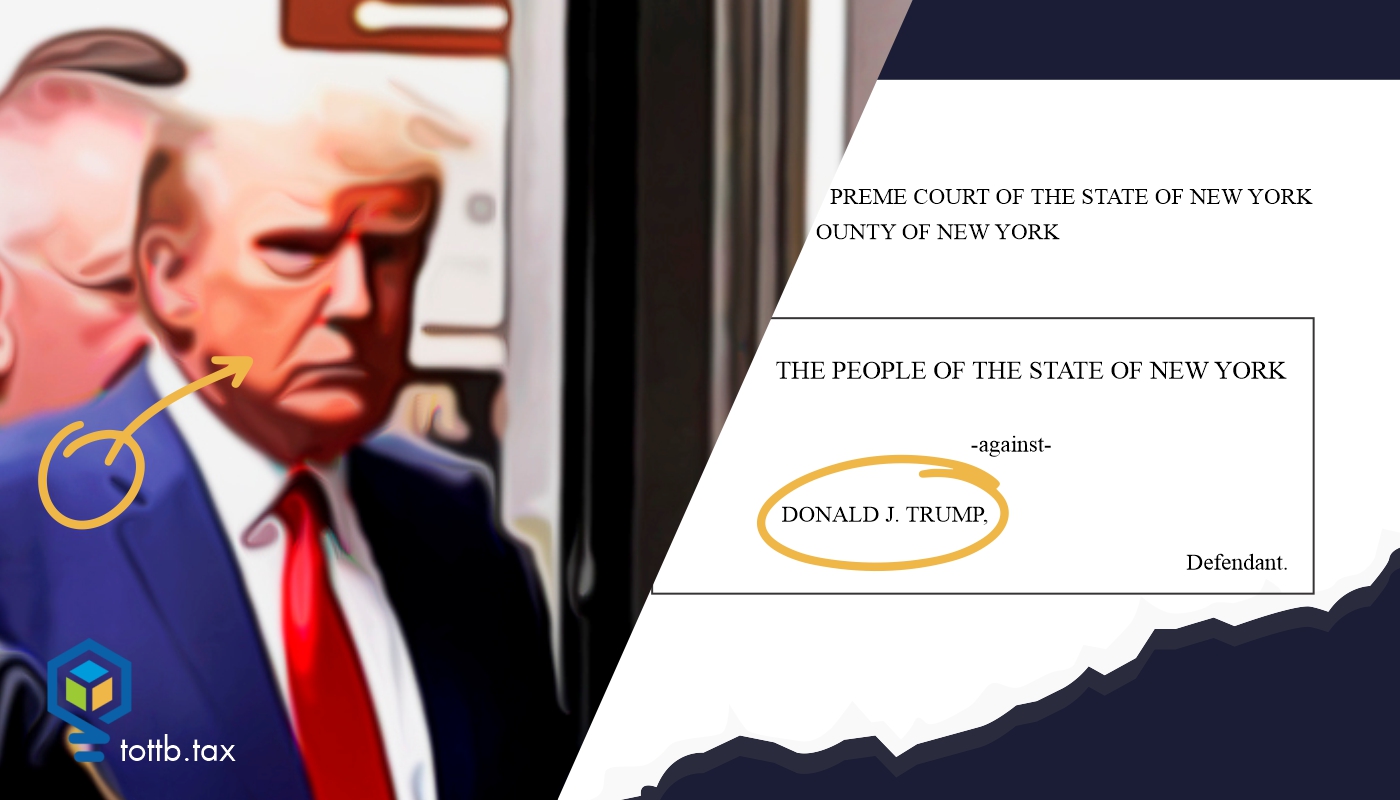
Reassessing R&D Structures After the Section 174 Changes
Recent changes to the tax treatment of research and experimental (“R&E”) expenditures may warrant a fresh look at existing intellectual property (“IP”) and research and development (“R&D”) structures. This article examines whether taxpayers should revisit decisions regarding the location of R&D activities, IP ownership, contract R&D arrangements, and related transfer pricing policies in light of the evolving legislative landscape, and how the interaction of Sections 174, 168(k), 59(e), and 163(j) can be used to calibrate a tax-efficient result.

Form 1099 Reporting Thresholds Have Changed
The Form 1099 reporting thresholds have changed from the old, familiar $600 amount to $2,000 for 2026. But because nothing is ever easy or straightforward, the threshold hasn’t changed for “all” transactions that might end up on a 1099, particularly with Form 1099-MISC.

What Do You Ask Indie Game Developers at Tax Interviews?
When you take on a new client, the tax interview is one of the most crucial elements of ensuring that their tax documents are prepared correctly. Both individual and business clients should provide you with a road map for their current tax situation, what they expect it to look like in the near future, and how your tax planning and preparation skills will help them with their business or financial goals. To focus specifically on business clients, questionnaires that the client fills out beforehand can efficiently cut down on facetime. This allows you more time to ask focused questions and learn about your client’s business needs and environment. But if your client is a game developer, specifically an indie game developer, there’s some nuanced questions you should ask in person or as an addendum to your questionnaire after you’ve read about the basics of doing business with game developers.
