
Consider this article your periodic reminder that, for married taxpayers, filing jointly is an election and not the default (and certainly not the only) filing status option. It is important in a busy practice to remember to offer this option to clients who may benefit from filing separately, even if they don’t ask.
The SALT Cap
For most benefits (including the standard deduction), the MFJ benefit is double what a single or MFS filer would get. For the SALT cap, the MFJ benefit is cut in half. I know this seems to be a semantic nit, but if Congress wanted to raise the SALT cap from $10K to $40K (which they did), the baseline benefit would usually be the amount for a single filer. Then double that for MFJ. Instead, the baseline is MFJ (the elected filing status) and the benefit is halved for MFS filers. In any case, there are some basic math advantages to be gained by filing separately, as shown from the tweet below.
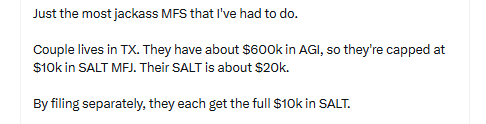
In the quoted tweet, the married couple paid about $20K in federally deductible state and local income taxes.[2] The SALT cap under OB3A is $40K but $20K for MFS filers.
Why are they then capped at $10K? Because the SALT cap under OB3A is phased out at higher incomes.[3] The tweet states that the couple has about $600K in AGI. That’s $100K over the $500K in income where the phase out begins. The calculation reduces the deduction by 30% of the amount over the phase out but the deduction cannot be reduced to less than $10K. In this example, the couple maxes out the phase-out amount ($100K * 30% = $30K; $40K – $30K = $10K in available SALT deduction).
MFS filers are subject to the same calculation, but the phase out begins at $250K. Splitting the AGI equally, means that each taxpayer is $50K over the threshold. At first, there would seem to be no benefit to filing separately—30% of $50K is $15K. The $40K SALT cap is $20K for MFS filers ($20K – $15K = $5K). Each filer would get $5K in SALT deduction. But wait! The law says that the calculation cannot reduce the cap below $10K! Bam! Each MFS filer magically gets an additional $5K in SALT deduction.[4] It’s weird but it works and it should not be overlooked.
The Tradeoffs
Everything, and I do mean everything in tax has a corresponding trade off.[5] The MFS filing status is going to work best for high-income earners and those without kids. Why? Because many tax credits, exclusions, and deductions are not available to MFS filers:
- Earned Income Credit (in most cases)
- Elderly or Disabled Credit (unless spouses lived apart all year)
- Child and Dependent Care Credit (in most cases)
- Adoption Expense Credit or exclusion (in most cases)
- Education Credits (American Opportunity Credit & Lifetime Learning Credit)
- Premium Tax Credit and Advance Premium Tax Credit (in most cases)
- S. Savings Bond interest exclusion
- Student loan interest deduction
- No tax on tips
- No tax on overtime
- Enhanced senior deduction
Here’s where you show your value as a tax professional. Use the planning tools available in your tax software to run an MFS analysis for the client to see what they lose and potentially gain by filing separately. For example, in middle income households in higher tax areas, if one spouse has tips or overtime, the loss of that deduction could outweigh the additional deduction under the SALT cap rules.[6]
That said, depending on the couple’s AGI, and whether or not they have qualifying children and/or qualifying expenses, filing separately could still be the best option. For example, many taxpayers “income out” of the available education credits and the student loan interest deduction, so losing those by filing separately may not be a big deal. Or perhaps the taxpayers are under age 65, are salaried DINKs and have employer-sponsored medical coverage. For the most part, the list of disallowed benefits won’t apply to them at all, but the extra $10K in SALT deduction could save them $2400 to $3700 in taxes. Take the money!
Beyond the amount of the tax liability, it is important to note that joint filing creates a “joint and several” tax liability, which effectively means that either spouse can be held responsible for the entire amount of the tax. If the marriage goes sideways and the tax return is examined and the IRS determines a deficiency exists, the only way the joint and several liability can be overcome is by filing for innocent spouse relief, which isn’t a guarantee that the spouses will be treated equitably with respect to the liability.
Additionally (and I know there are tax professionals who will disagree with me on this[7]), filing separately can allow a tax practitioner to adjust income amounts between spouses to optimize the amount of student loan repayments in order to help clients who may be high income but who may have cash flow issues. For example, clients who have a mortgage but who would like a bit of a cash cushion each month. Reducing the required monthly student loan repayment amount allows the clients to decide if they want to add an additional amount to the monthly student loan payment or keep it in case of emergency.
Where incomes are unequal (in non-community property states), choosing MFS could allow a spouse with extremely limited income to contribute to an IRA account that they would otherwise be phased out of. Contributions are phased out at much lower income limits for separately filing spouses where one spouse is covered by an employer-sponsored retirement plan.[8] Nevertheless, if one spouse has, for example, a really small Schedule C business and the other is a higher income wage earner, the Schedule C spouse could theoretically be allowed to make an IRA contribution that would be disallowed had the couple filed jointly.
State Issues
It is always important to remember to check state tax law for the return(s) you are preparing. Some states (for example, Arizona) do not necessarily follow federal law with respect to filing status—that is, a married couple could file a joint federal return and separate state returns or vice versa. Again, you show your value by knowing the rules and by using your tax software to analyze the benefits of the available filing statuses at both the federal and state level.
In community property states with state income tax (for example, New Mexico) if you have access to both spouses’ income and withholding, many of the benefits from married filing separate may go away because state law won’t allow you to do an unequal allocation of income and withholding. You are legally required to split all items of income and withholding 50-50. Often this causes both spouses in the couple to income out of the benefits that would be available if an unequal allocation of income were allowed.
In community property states with no state income tax (for example, Nevada[9]), state law allows the couple to divide their income and withholding in any way the couple can agree upon.[10] Again, different community property states define items of community property differently so it is important to understand the laws that apply for the state income tax returns that you are preparing.
Income allocations for individuals filing separately are made by attaching Form 8958 to the filer’s Form 1040. Note that it can be problematic if you are in a 50-50 community property state and only have access to one spouse’s information. In that case you can use the information for the spouse you have and do “zero allocations” for the other spouse.[11] You can’t get blood from a turnip and sometimes spouses do not share tax professionals or financial information. Do the best you can with the information you have to prepare an accurate tax return for the spouse for whom you are working.[12]
Changing Filing Status
Filing jointly is not only an election, it is an irrevocable election. Pardon me for getting biblical here, but this is how I remember it: “What God has joined together let no man put asunder.” You cannot amend a jointly filed return into two separately filed returns. You can, however, amend filing separate returns to a joint return because again filing a joint return is the election.[13]
Keep this irrevocability in mind, especially when you’re under tight deadlines and maybe are unsure of which is the more optimal filing status and perhaps don’t have a full set of income and withholding information and/or don’t have time to figure it out. You can file an extension with both spouses’ names and TINs and still file MFS. The extension simply grants the taxpayer(s) additional time to file the return (and make the election to file jointly). It does not bind the filing status, it simply preserves the ability to make the joint filing elections (as well as so many other elections).
Best Practices
Do some proactive data mining and client analysis. You may have couples that have been with you for a while and who have been filing jointly, and no one has given much thought to the filing status. Check income levels and life events (for example, new jobs or promotions that include big raises) for your married filers. Offer a married filing separate analysis to clients who might benefit from filing separately in the summer when you have more time or possibly in the late fall/early winter before filing season really gets going. This is a form of tax planning, it’s not return preparation. If you’re doing and documenting a thorough analysis of a change in filing status, you should charge for the work.
If you’re filing separate returns, charge for two returns. You are preparing two returns. You are incurring separate liability for each return you prepare. Clients aren’t always going to like this but that is why you charge for the analysis separately from the return preparation engagement. You have to do the analysis to make sure that there is enough economic advantage to filing separately to cover the cost of that second tax return. What you charge for the second return is, of course, up to you.
I’ve said it before and I’ll say it again—document, document, document.[14] You need to retain your notes and work papers. These documents prove that you’ve run the numbers and that the additional expense and administrative pain required to file separately are adequately compensated by the tax savings. They also explain the reasoning behind not making the election to file jointly (for you, your staff, and whoever may do these taxpayers’ return(s) after you).
Again, I recommend having both clients sign off on something that explains why they refused the joint filing election and chose to file separately. Perhaps something that includes a summary analysis of the numbers.[15] People forget and you want to be sure that you have covered your assets.