Retirement Tax Planning — Retirement Plans for the Sole Proprietor
Many of the same tax advantages perceived as being only available with entity taxation are also available to Schedule C sole proprietors and that includes funding retirement plans. It’s perfectly OK to start and continue to run a business as a sole proprietorship filing a Schedule C for when it makes financial and administrative sense to do so. There are a number of advantages to having a retirement account. Of course, when you contribute to a retirement account, you can deduct your contributions from your taxable income. This can result in significant savings come tax time. Additionally, the money in your retirement account grows tax-free. This means that you can potentially earn a lot more on your investment than you would if it were subject to taxation. A retirement account gives you the peace of mind that comes with knowing you have a cushion to fall back on in retirement. No matter what happens in the markets, you will always have access to your retirement savings. This can provide a great deal of security during uncertain economic times. While retirement accounts can be a great way to save for the future, there are also some potential drawbacks to consider. For one thing, retirement accounts often come with strict penalties for early withdrawal. This means that if you need to access your savings before retirement age, you may be subject to significant fees. Additionally, retirement accounts can be complex and confusing, making it difficult to keep track of your progress. While retirement accounts can be a helpful tool for saving, it’s important to be aware of the potential drawbacks before you decide as a sole proprietor whether or not to open one. Click here to explore the different types of retirement plans available to sole proprietors and the pros and cons of each.
Read More
Help Your Clients Implement a Fortune 500 CFO Strategy
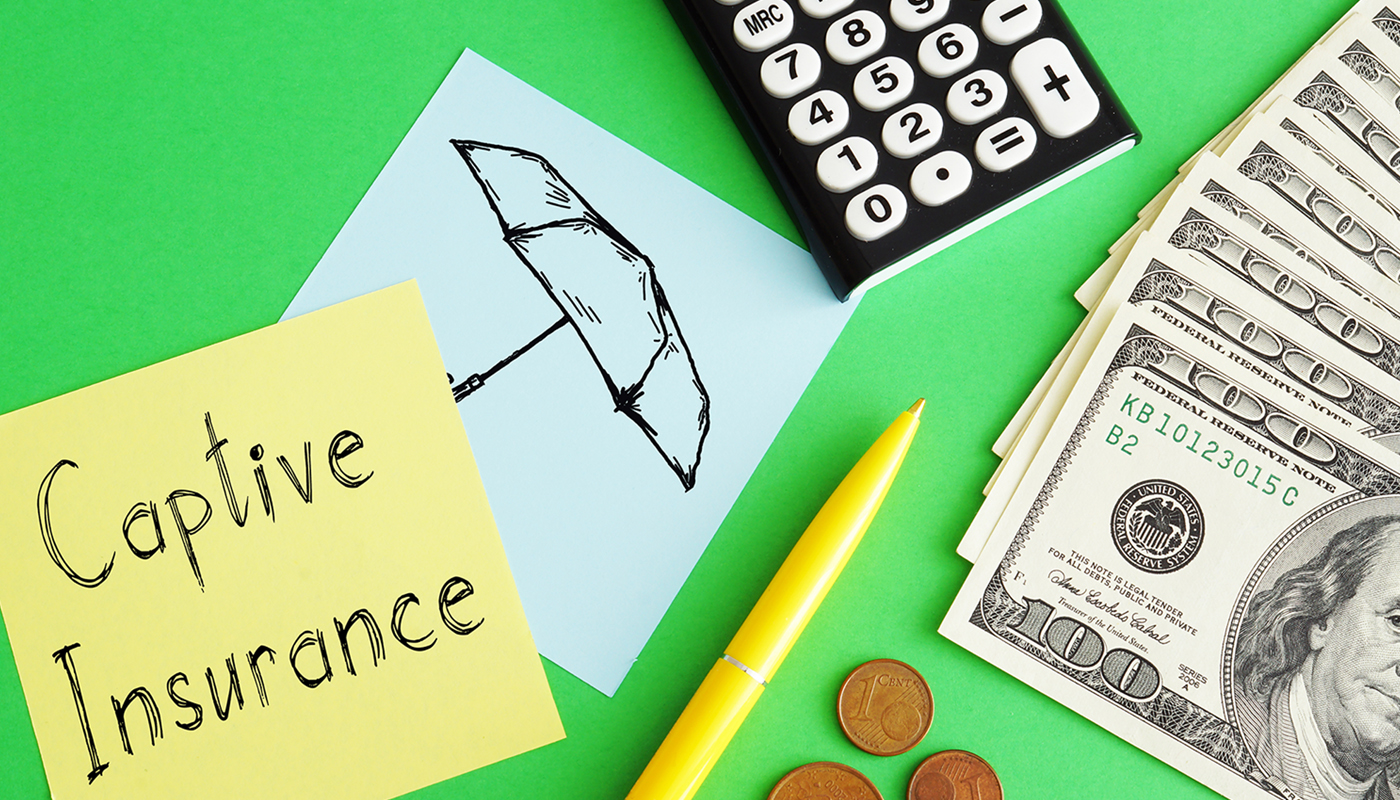
For decades, some of America’s largest corporations have used a financial strategy that gives their CFOs greater control over insurance costs, helps them finance risks the commercial market handles poorly and creates an opportunity to retain underwriting profit when losses come in below expectations. Approximately 90% of Fortune 500 companies have captive insurance subsidiaries.¹ Historically, the economics favored organizations with substantial capital, large insurance programs and the resources to support their own insurance operations. Small and midsize businesses rarely had the scale to justify the cost and complexity. That equation has changed. A mature network of specialized insurance professionals and structures now allows qualifying privately held businesses to pursue many of the same risk-financing advantages. Federal tax law can further improve the economics for certain smaller insurance companies. For CPAs and tax professionals, this creates an advisory opportunity. The challenge is recognizing which clients could benefit and what conditions must exist before recommending it.
Structured Installment Sales Making Comeback – How Good A Tool Is It?
Structured Installment Sales (SIS) have been making a comeback. Historically low interest rates starting in 2011 made them go out of favor. Starting in 2018, insurers started coming back into offering them. MetLife expanded its SIS solution to 49 states, Puerto Rico and D.C. in 2022. You need to know about SIS and it deserves a place in your toolbox. You might not be using it as often as the toolmakers imply. I took a look at SIS in 2023 and was a little more enthusiastic about it than I am now. Let’s dig in.
Assessment Statutes and Document Retention Best Practices
When it comes to document retention, my guiding policy is “If I don’t keep it, it can’t be stolen or subpoenaed.” That sounds cynical, but there’s truth in it. The smaller your data “surface area,” the less you have to manage in the event of a data breach (or, if you hold paper documents, in the event of a fire or break in). And, if a client or former client gets really sideways in divorce or criminal court, being able to say “I have a policy in place and I don’t keep records longer than three years” can provide you with a measure of peace. But what should your policy be? It depends, but relevant assessment statutes are a good place to start. This article reviews the IRS rules for assessing tax and provides some best practices for developing document retention policies for return preparation documents in your practice.