
Perhaps the most misunderstood aspect of partnership taxation relates to distributions. When a partnership distributes cash or property to its partners, the tax consequences can range from completely tax-free to significantly taxable, depending on how the distribution is structured and the partners' tax basis in their partnership interests. In this article, we'll explore the rules governing partnership distributions and how they impact partners' tax situations. More importantly, we'll look at strategies to structure distributions in the most tax-efficient manner possible – because the goal is not just to understand the rules but to use them advantageously.

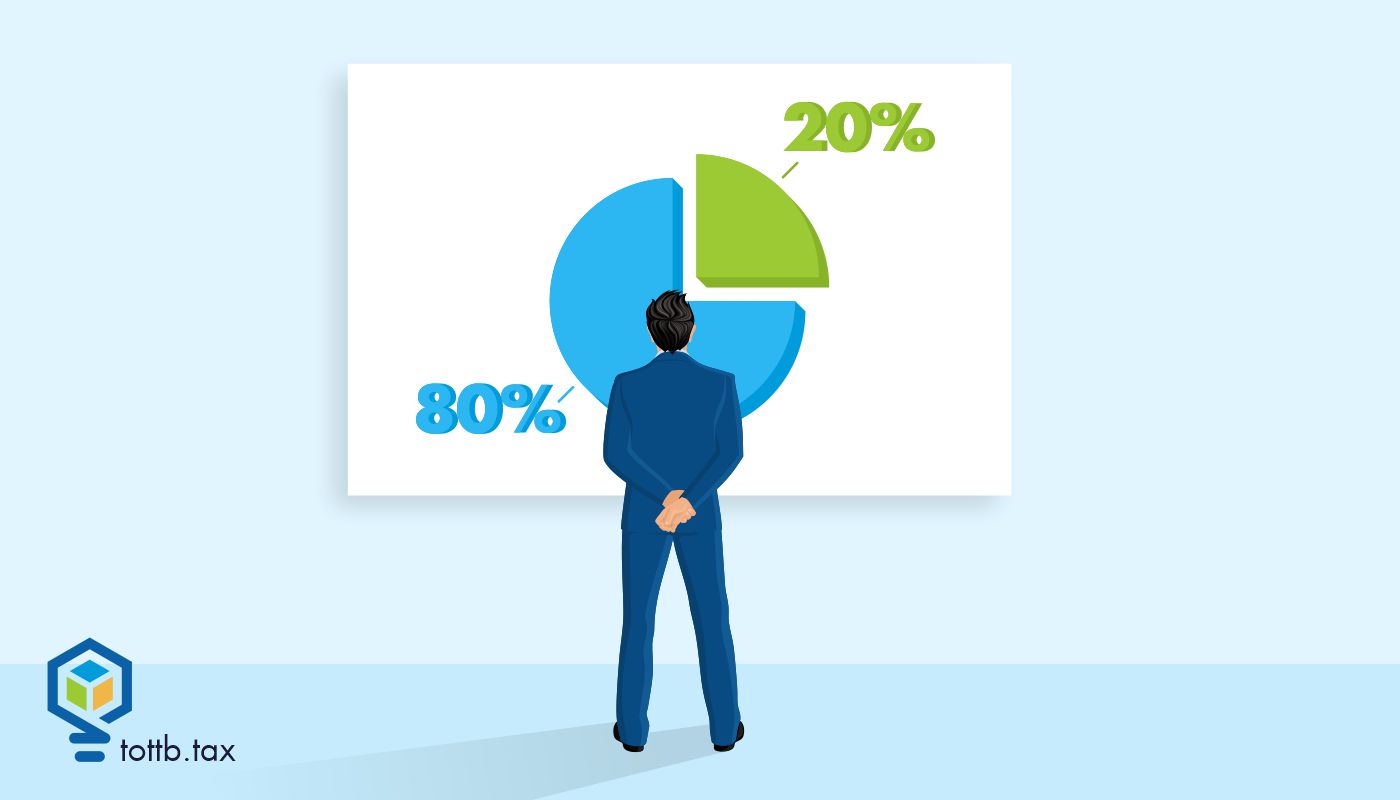
State Tax Planning with the “80/20 Company” Exclusion
Many multinational groups find that foreign-source dividends and other income earned by domestic affiliates are fully or partially subject to state income taxation, even where the federal system provides an exemption. This state-level “leakage” can be material – particularly in high-tax jurisdictions – and is often overlooked because the income appears sheltered at the federal level. For groups with predominantly foreign operations, a starting structure or a restructuring that causes one or more domestic affiliates to qualify as an “80/20 company” can substantially reduce or eliminate state taxation on that income.