
Investment Tax Credits (“ITCs”) and Production Tax Credits (“PTCs”, and together with ITCs, “RETCs”) have existed for decades and reflect the U.S. government’s commitment to incentivizing clean energy solutions in industry and commerce. The availability of RETCs was most recently extended by the Inflation Reduction Act of 2022 (“IRA”), which fundamentally transformed policy in this space by tying such credits’ expiration to the U.S. reaching certain targets for greenhouse gas reductions. While the recent change in Executive Branch leadership casts doubt over the longevity of RETCs, a full repeal seems unlikely given the scope and scale of domestic projects which utilize and benefit from such credits. This article discusses how RETCs may benefit both buyers and sellers in an increasingly uncertain environment.

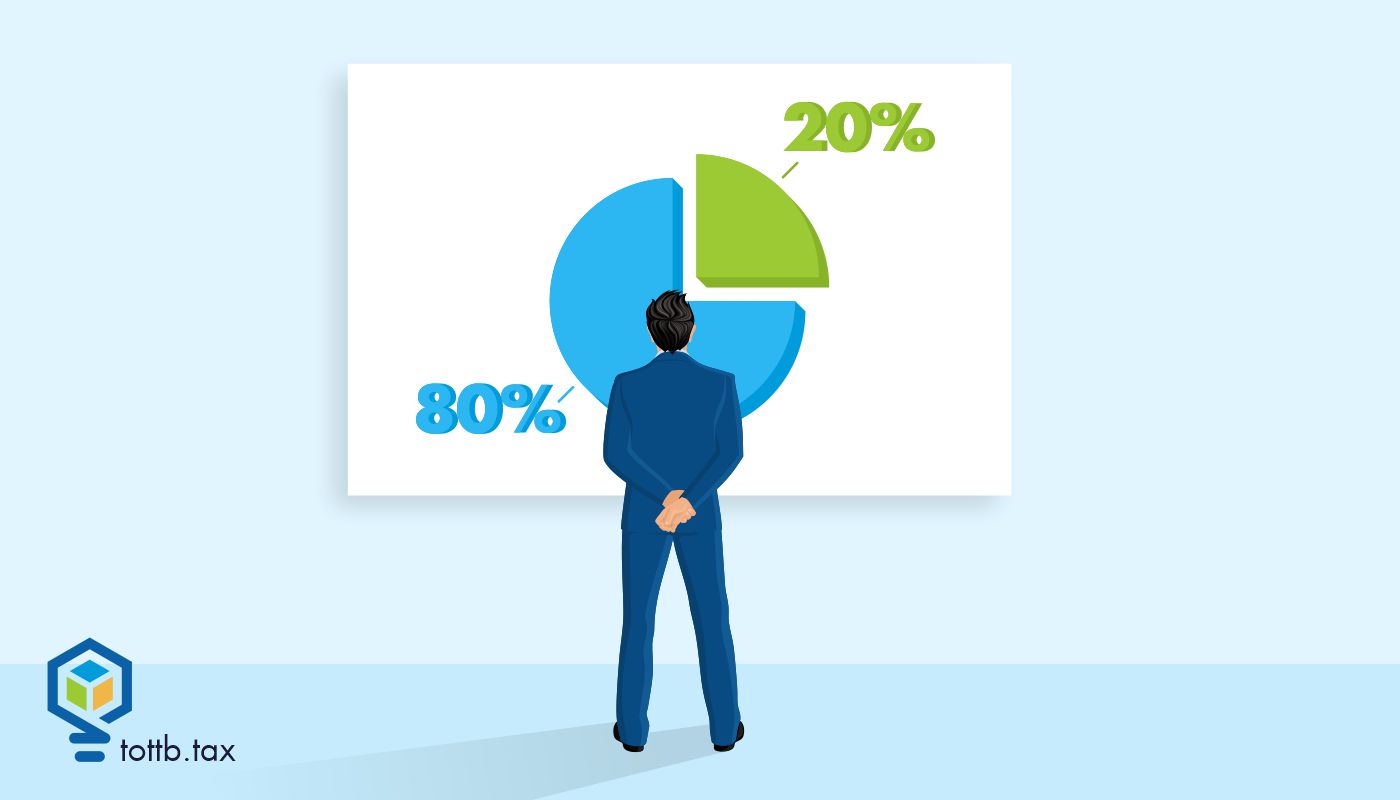
State Tax Planning with the “80/20 Company” Exclusion
Many multinational groups find that foreign-source dividends and other income earned by domestic affiliates are fully or partially subject to state income taxation, even where the federal system provides an exemption. This state-level “leakage” can be material – particularly in high-tax jurisdictions – and is often overlooked because the income appears sheltered at the federal level. For groups with predominantly foreign operations, a starting structure or a restructuring that causes one or more domestic affiliates to qualify as an “80/20 company” can substantially reduce or eliminate state taxation on that income.