
Tax season is in full effect, and it is likely that you are seeing and coping with the effects of poor administrative compliance on the part of your small business clients. Instead of bemoaning the fact that so many clients “don’t get it” use some of the time you’re spending on the return to prepare a list of administrative compliance items that the client needs to address. Then, set a (paid) planning appointment for later in the year to help the client address those items. If you do this, and if the client heeds your advice, next filing season more (if not always all) of the client’s administrative compliance will be in order by the time you start preparing their returns. It’s a win-win. Your client gets the opportunity to ensure that they are meeting administrative requirements that protect them from liability or penalties. You get cleaner paperwork (and peace of mind) moving into next filing season. Read on to learn more!

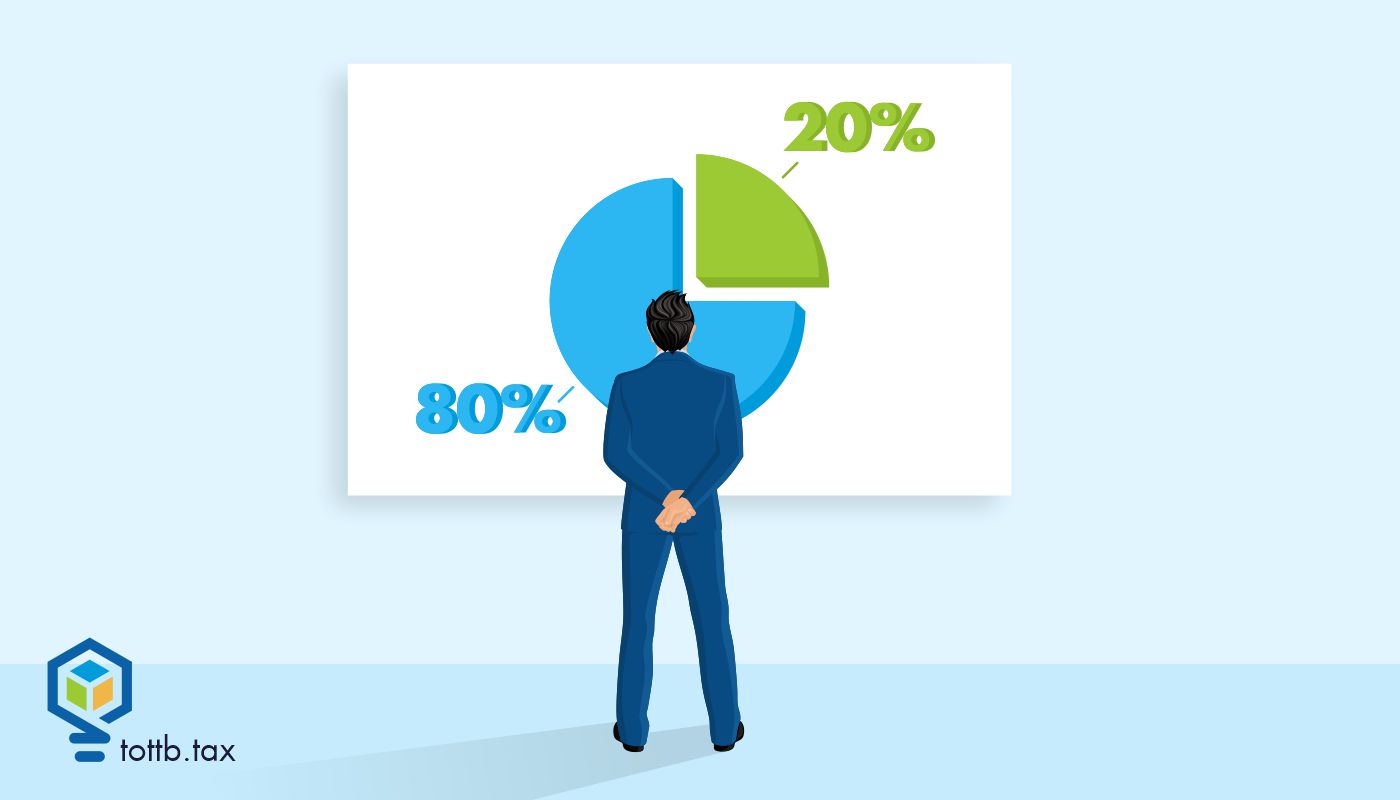
State Tax Planning with the “80/20 Company” Exclusion
Many multinational groups find that foreign-source dividends and other income earned by domestic affiliates are fully or partially subject to state income taxation, even where the federal system provides an exemption. This state-level “leakage” can be material – particularly in high-tax jurisdictions – and is often overlooked because the income appears sheltered at the federal level. For groups with predominantly foreign operations, a starting structure or a restructuring that causes one or more domestic affiliates to qualify as an “80/20 company” can substantially reduce or eliminate state taxation on that income.