

The “Busy Season” Myth: Why Accountants Stay Stuck Waiting for Time That Never Comes
If you’re a CPA, you’ve heard it a thousand times. People outside the industry say it like it’s a weather report: “How was busy season?” Firm owners say it to each other, as if it’s a shared badge of honor: “Just get through April 15.” Then it becomes, “After extensions.” Then, “After we rehire.” And after every “busy season,” there’s the crash. The weeks of 60–70 hours. The nights. The lost family time. The feeling that life is on hold until the deadline passes. Here’s the problem: tax deadlines don’t end—they shift. March 15. April 15. September 15. October 15. Year-end planning. 1099s in January. Treating the calendar like the boss means building firms stuck in constant reaction. The truth is, “busy season” isn’t a season. It’s a mindset. And it’s one of the most expensive mindsets we’ve normalized in public accounting.
READ MOREAnother Tax-Smart Way to Save for Retirement
Most clients are familiar with the well-known accounts to save for retirement, such as the 401(k) and IRA. Some clients might be able to supplement those with a lesser-known vehicle as well. A life insurance retirement plan (LIRP) is a type of permanent life policy with a cash value basically funded by overpaying premiums. The money can eventually be taken as a tax-free loan against the policy for anything from medical expenses and long-term care to supplemental retirement income to, for the wealthy, the payment of taxes on large estates.
Read More
Taxes & Taxidermy: Rampaging Through The Tax Code On The Back Of A Stuffed Rhinoceros
Is the taxidermy fee for a stuffed bear deductible? If so, should I depreciate it? What would the basis and class life be for depreciation? Those are real questions asked in a group chat with some colleagues. Of course my answer was “It depends.” And, like all good tax professionals, I proceeded to ask a series of follow-up questions. And, like a good writer, that got me to thinking about all of the tax-related case law surrounding taxidermy and what it can teach us—it’s more than one might think.
Read More
The Power Trio for Accountants: Reviews, Testimonials, and Case Studies to Drive Growth
As an accountant with a firm to grow, the power is in your hands. Your digital presence, or lack thereof, can often determine your firm's growth. The good news is that reviews, testimonials, and case studies are potent tools that put you in the driver's seat of bolstering your reputation and attracting new business. But what is the difference between these three, and how can you strategically use each to scale your accounting practice?
Read More
An Analysis of the OBBBA’s Trump Accounts (Part 1)
The One Big Beautiful Bill Act, signed into law by President Trump on July 4, 2025, added a new tax saving tool for minors, the aptly named Trump Accounts. In this article, I go over the details of the new Trump Accounts. In part II, I will discuss some of the potential tax planning opportunities and pitfalls related to the new accounts.
Read More
Student Loans After the OBBBA Part 1: New Rules Every Advisor Needs to Know
Big changes are coming to the student loan world (yet again), and they’re not the kind you can just skim past. The One Big Beautiful Bill Act (OBBBA) has reshaped how much students will be able to borrow, how they’ll repay it, and which programs will qualify for federal aid going forward. For financial and tax professionals, these shifts aren’t just policy updates. They’ll set the stage for how you’ll advise clients for years to come… and could even change the way you manage your own student loans. In Part 1 of our OBBBA student loan series, we break down the nuts and bolts of these new rules to help advisors (and borrowers) get some clarity on the collective question: “Seriously, what’s going on with student loans?”
Read More
IRS And Courts Have Wisdom to Offer Startup Businesses
There is a wealth of business wisdom in a fairly unlikely area. All the businesses involved lost money, sometimes enormous sums. The source is the litigation and regulation around Code Section 183 of the Internal Revenue Code – Activities not engaged in for profit. In order to deduct those losses against other income, taxpayers need to convince the IRS or the court that they had an honest objective of making a profit. The determination of whether an activity is carried on for profit is made by reference to objective standards. Is it possible that following those standards might contribute to you being profitable? It’s worth thinking about.
Read More
TAX COURT ROUNDUP – October 2025
There are new insights and old unresolved questions in this month's instalment. There's always the old and new.
Read More
2025 Winter Education Series Event Calendar
Think Outside the Tax Box proudly presents the 2025 Winter Education Series! This October through December, we are bringing our loyal subscribers five webinars featuring some of the brightest minds in tax. Each high quality webinar is filled with engaging content, actionable insights for your clients, and they all come with continuing education credits for those who qualify. All of this is included in your regular subscription! Check out what we've got in store for you!
Read More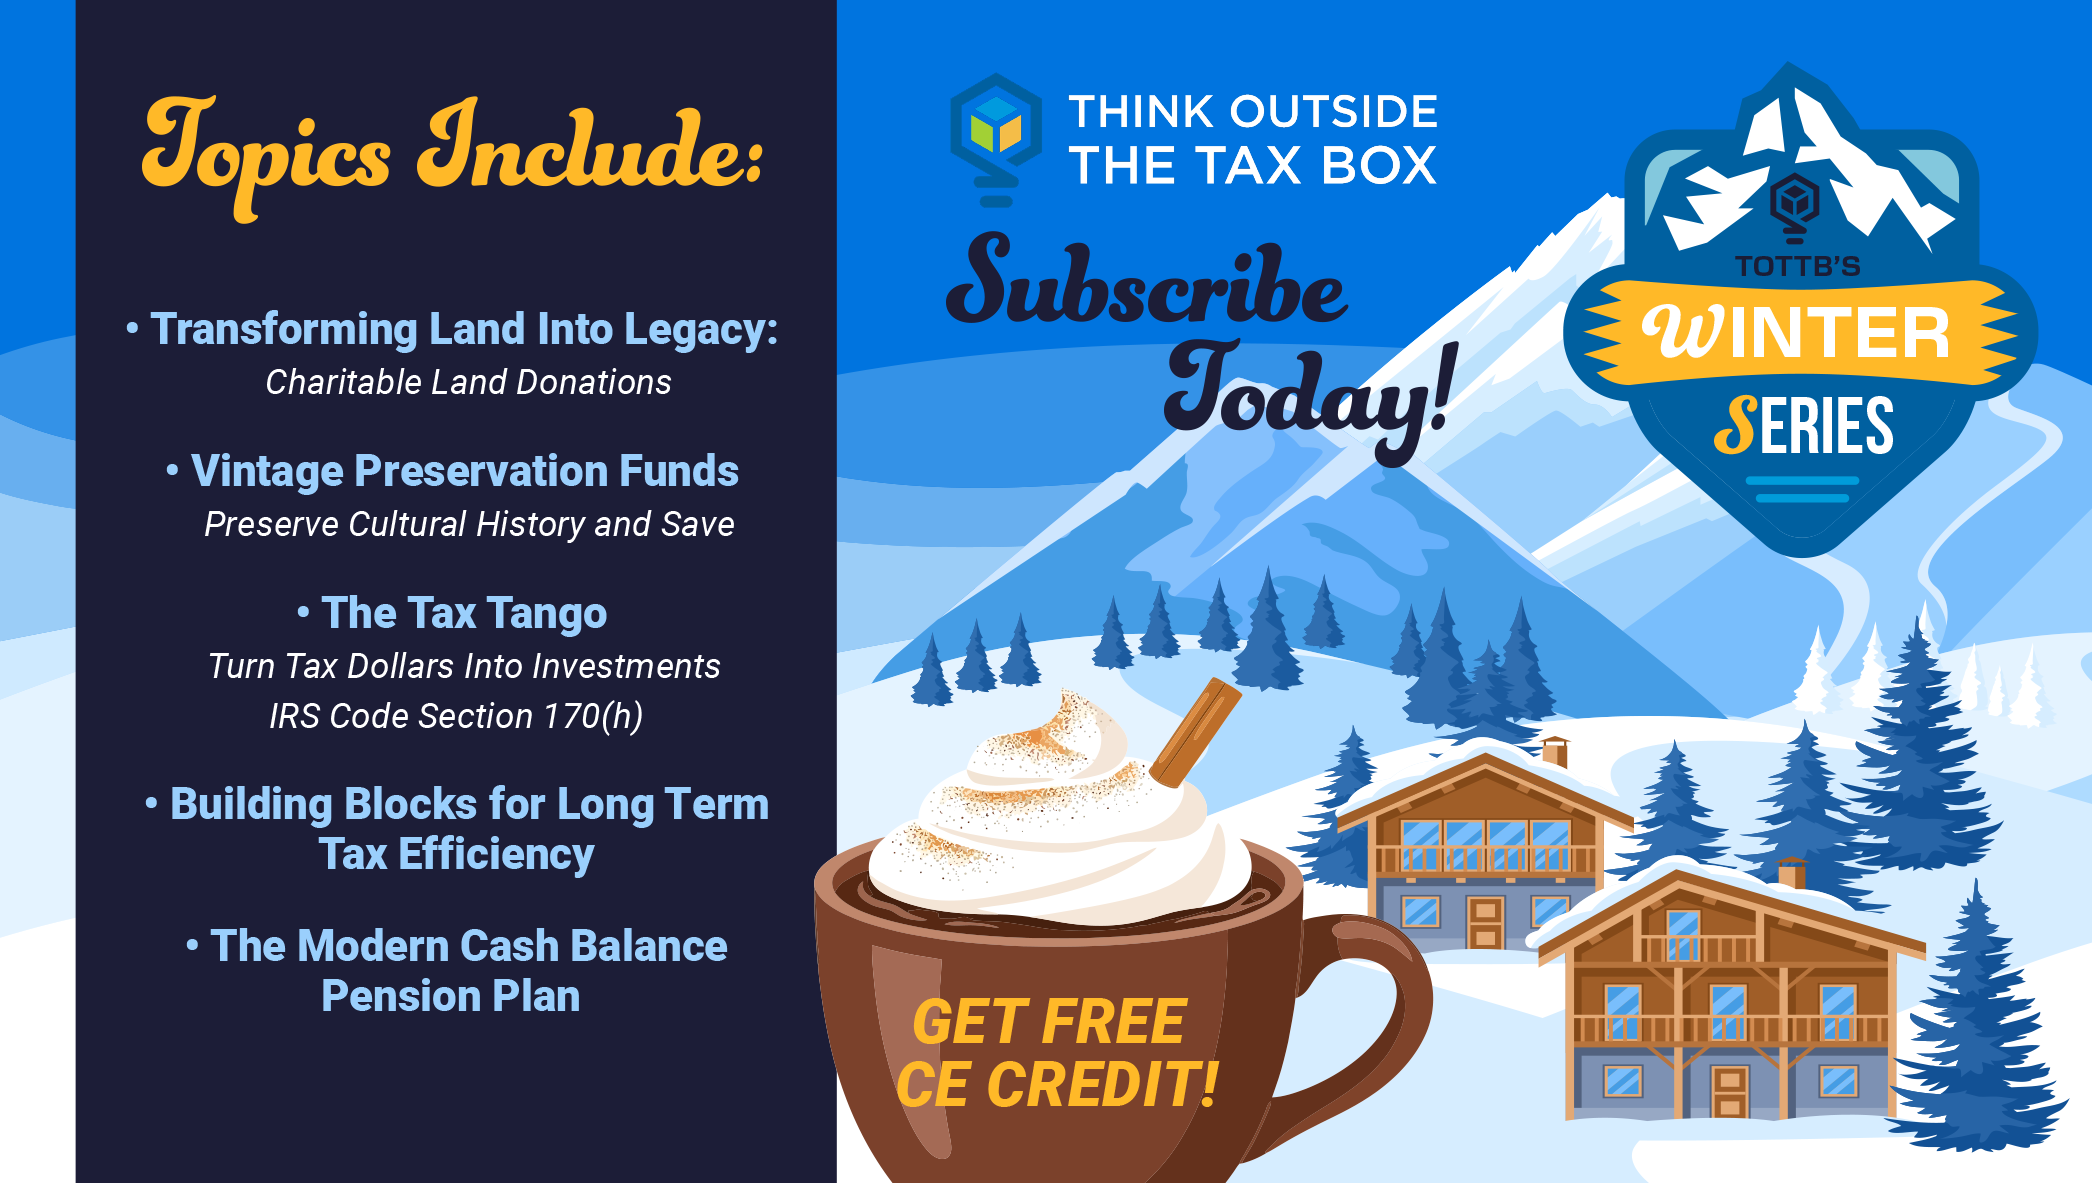

The “Busy Season” Myth: Why Accountants Stay Stuck Waiting for Time That Never Comes
If you’re a CPA, you’ve heard it a thousand times. People outside the industry say it like it’s a weather report: “How was busy season?” Firm owners say it to each other, as if it’s a shared badge of honor: “Just get through April 15.” Then it becomes, “After extensions.” Then, “After we rehire.” And after every “busy season,” there’s the crash. The weeks of 60–70 hours. The nights. The lost family time. The feeling that life is on hold until the deadline passes. Here’s the problem: tax deadlines don’t end—they shift. March 15. April 15. September 15. October 15. Year-end planning. 1099s in January. Treating the calendar like the boss means building firms stuck in constant reaction. The truth is, “busy season” isn’t a season. It’s a mindset. And it’s one of the most expensive mindsets we’ve normalized in public accounting.

The Tips Deduction and the Self-Employed: Potholes Everywhere
By now, tax professionals and taxpayers are familiar with the fact that the One Big Beautiful Bill (OBBBA) created a new tax deduction for tips received. What we want to look at in this article is — how do self-employed taxpayers handle this deduction?
The Succession Plan You Keep Meaning to Write
I have a friend who has been retiring “in about two years” for the last five years. He is 67, runs a successful practice with about 400 returns, and specializes in tax planning. He has never had the practice valued. He also has no succession plan in the event he does not come back from his next fishing trip. This is not unusual. This is typical. The 2020 American Institute of Certified Public Accountants (AICPA) firm succession survey found that only 6% of solo and sole practitioners had a practice continuation agreement in place. Nearly half of those surveyed said they knew they needed one and had no idea how to start. That second figure is the one that gets me, because it is not denial. Our colleagues know exactly what is at stake and are stuck. Let us get unstuck.
